PCCA Cotton Market Weekly
November 16, 2026
The Week Ahead
Cotton prices held their own last week despite pressure from outside markets. With the November supply and demand report released and both major index rolls complete, the market will be looking for a new narrative to give prices direction.
- The economic calendar is relatively quiet ahead of Thanksgiving, with retail sales data on Tuesday and minutes from the Federal Reserve’s latest meeting on Wednesday. The U.S. dollar reached a 19-month high last week, and markets are now fully expecting an interest rate increase in December. Any further strength in the dollar could make it more difficult for U.S. cotton to compete internationally (almost all U.S. cotton gets exported).
- Speculative traders have spent much of the past two months reducing their exposure to agricultural commodities. While this leaves room for buyers to return, the market will likely need encouraging news to attract renewed buying interest. Updated CFTC data will be released Monday and Friday.
- Trade and export demand will be important to watch this week, particularly given the competition from Brazil. President Trump and Chinese President Xi Jinping are expected to meet Thursday, along with Russian President Vladimir Putin. The cotton market will be looking for concrete details regarding tariffs and potential agricultural purchases.
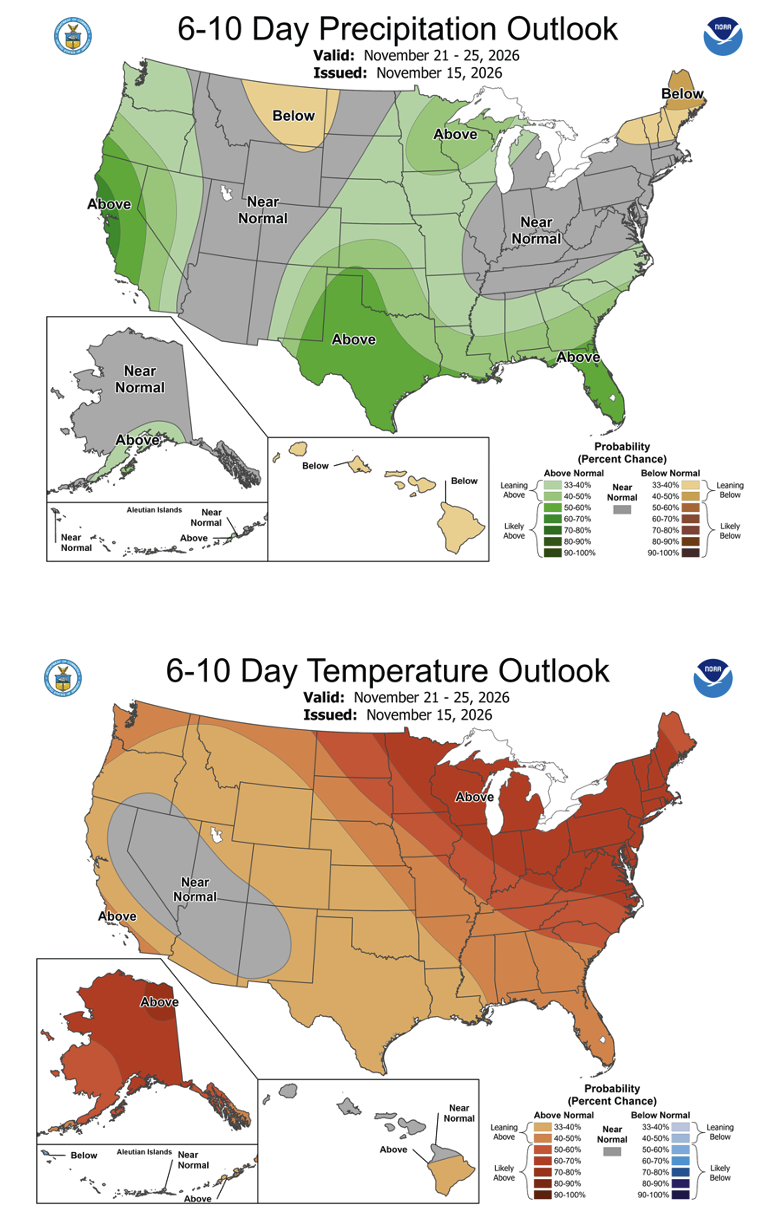
- Harvest and classing activity across the Southwest will provide a better understanding of the size and quality of this year’s crop. Lower color grades, higher leaf content, and extraneous matter are negatively impacting loan values. Increased chances for rainfall over the next two weeks could further deteriorate quality and delay harvest.
 Market Recap
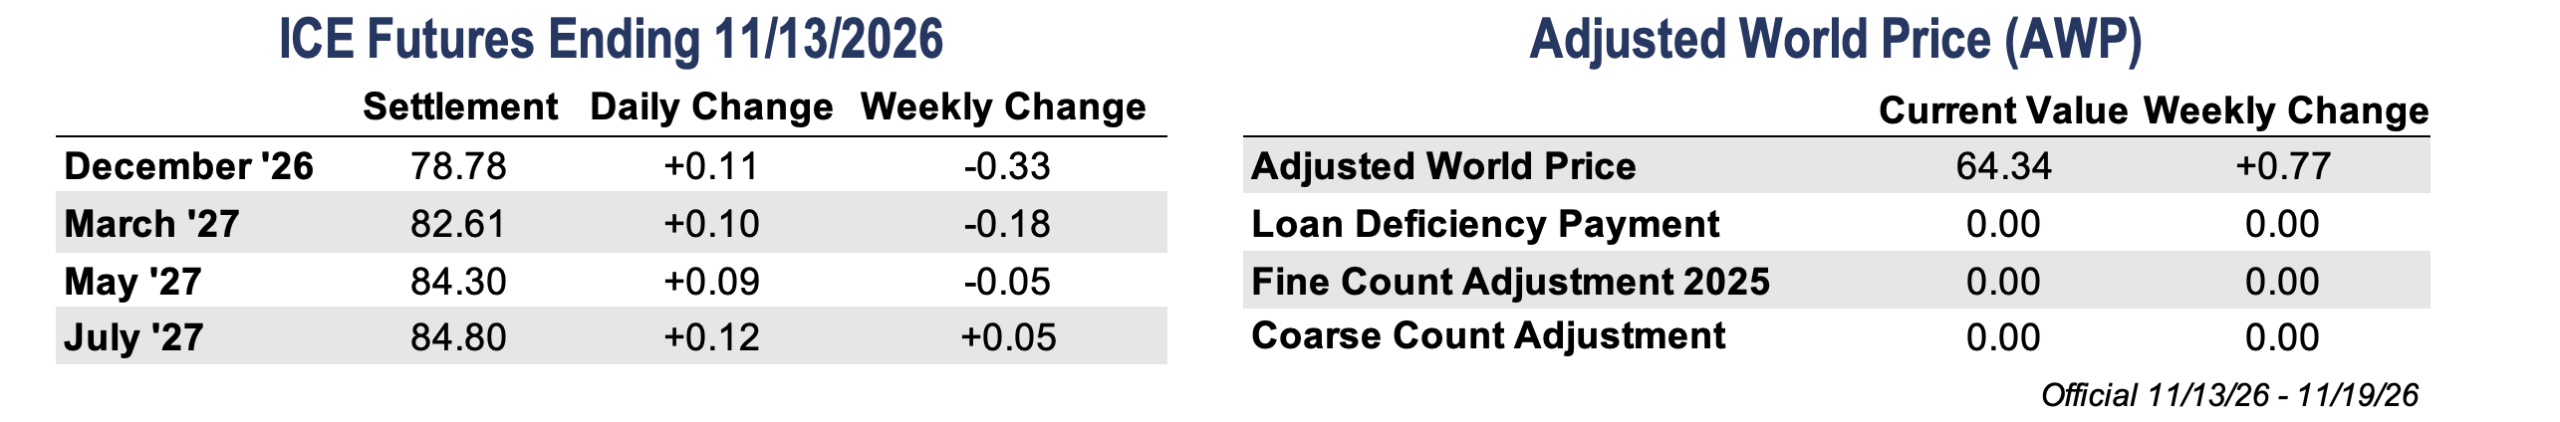
- Cotton futures traded in a relatively narrow range this week, with December settling Friday at 78.78 cents per pound, down 33 points for the week. March futures lost 18 points to finish at 82.61 cents per pound as trading activity shifted toward the new front-month contract.
- Much of this week’s trading was driven by the Goldman Sachs Index roll rather than changes in market fundamentals. The roll is the point on the calendar when investors close out their long positions and put on new ones in the next contract month. December options expired on Friday, with First Notice Day approaching on November 23.
- The December/March spread widened to a new contract low of 405 points on Tuesday before narrowing to 383 points by Friday. The spread settled at its widest level since 2009, with March trading at a premium that covers much of the cost of storing and financing cotton for later delivery. Certificated stocks have also increased considerably since early November, reaching 79,431 bales on Friday.
- Tuesday’s supply and demand report brought modest reductions to U.S. and global ending stocks, but the market showed little reaction. A stronger U.S. dollar and renewed selling in technology stocks added pressure, although cotton held relatively steady.
- While buying interest at lower prices and export demand have boosted cotton, ample global supplies and strong competition from Brazil could limit upward momentum in the near term.
- Certificated stocks have also increased considerably since the beginning of November, reaching 79,431 bales on Friday. The wide December/March spread makes holding cotton for later delivery more attractive, which could help explain some of the increase.
- Looking ahead, March futures will take center stage as December approaches expiration. While buying interest at lower prices and export demand have offered some encouragement, ample global supplies and strong competition from Brazil could limit near-term upward momentum.
Economic and Policy Outlook
- Inflation came in stronger than expected last week, with consumer prices rising 0.4% in October and core inflation increasing 0.3%. Wholesale prices were up 6.5% from a year ago, the largest annual increase since November 2022.
- Persistent inflation and a stronger labor market have markets pricing in a quarter-point interest rate increase in December. The U.S. dollar reached a 19-month high, while Treasury yields moved higher. Higher borrowing costs and a stronger dollar add to the challenges facing U.S. agriculture.
- Congress returned to Washington last week following the midterm elections, with a crowded legislative agenda and roughly 20 legislative days left in the year. While agricultural committee leaders have expressed optimism about completing the Farm Bill, disagreements over nutrition programs are still holding up negotiations. With a government funding deadline approaching on December 11 and control of Congress changing in January, the window to pass a new Farm Bill is narrowing.
Supply and Demand Overview
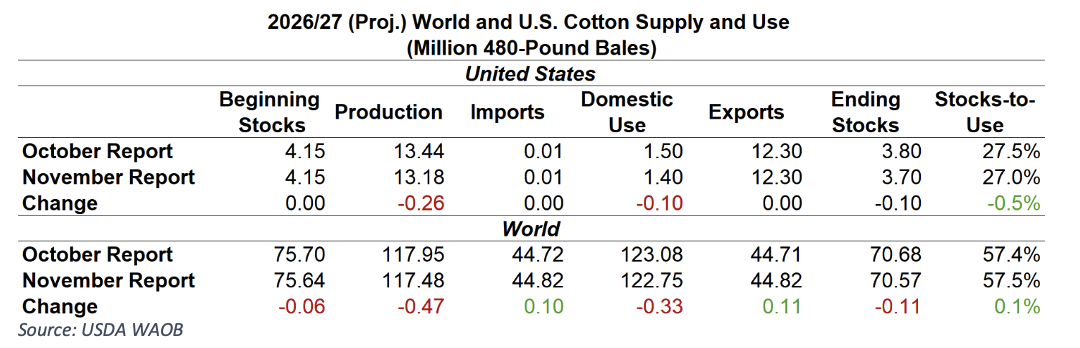
- November’s supply and demand report brought a reduction in U.S. cotton production, with most of the decrease coming from the Southwest. USDA lowered its production estimate by 267,000 bales to 13.18 million, as the national average yield fell 15 pounds to 775 pounds per harvested acre. The Southwest accounted for 250,000 bales of the reduction, with Texas production falling to 4.10 million bales and Kansas to 80,000 bales. Oklahoma production increased slightly to 200,000 bales.
- The smaller U.S. crop pushed ending stocks lower, although weaker domestic consumption offset some of the reduction. Mill use was lowered 100,000 bales to 1.40 million, while exports were unchanged at 12.30 million. Ending stocks declined 100,000 bales to 3.70 million, bringing the stocks-to-use ratio down slightly from 27.5% to 27.0%.
- The global balance sheet tightened slightly, but mill use paused its upward trend. World production declined 470,000 bales to 117.48 million, driven by smaller crops in India, Turkey, Argentina, and the United States. Larger crops in Australia and China partially offset those reductions, while Brazil’s production estimate was unchanged. Global mill use fell 335,000 bales to 122.75 million, and ending stocks declined 110,000 bales to 70.57 million.
- For the week ending November 5, Upland net sales for 2026/27 totaled 157,300 bales, down 43% from the previous week and 25% below the prior four-week average. Vietnam led purchases with 56,100 bales, followed by Turkey and Mexico. An additional 30,800 bales were sold to Malaysia for the 2027/28 marketing year.
- Weekly Upland shipments improved to 171,400 bales, up 24% from the previous week and 8% above the four-week average. Vietnam, Bangladesh, and Pakistan were the leading destinations.
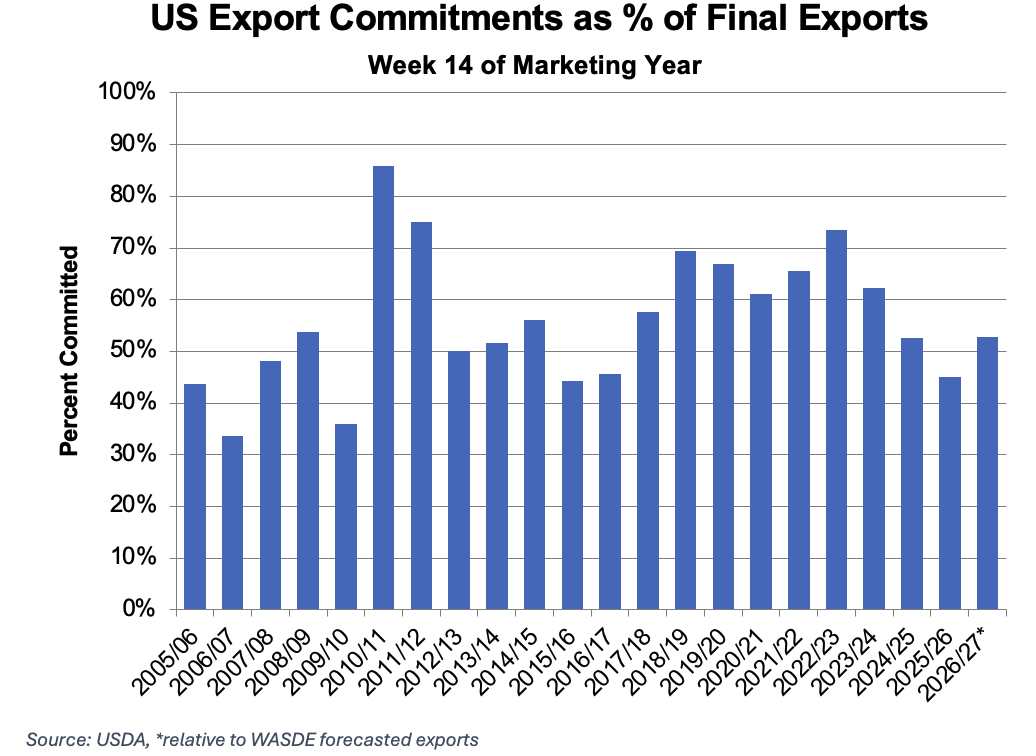
- Although sales slowed from last week’s strong showing, the improvement in shipments was encouraging. Export commitments are running ahead of last year’s pace, but shipments will need to pick up further to meet USDA’s export projection. With Brazil actively competing for business, maintaining steady sales and improving the pace of shipments will be important in the months ahead.
- Pima net sales totaled 15,200 bales, a noticeable increase from the previous week, led by India and Peru. Weekly Pima shipments reached 7,000 bales, down 2% from the previous week, with India, Bangladesh, and Vietnam receiving the largest volumes.
 The Seam®
- As of Friday afternoon, grower offers totaled 17,987 bales. The past week, 4,707 bales traded on the G2B platform received an average price of 73.45 cents per pound. The average loan redemption rate (LRR) was 54.53, bringing the average premium over the LRR to 18.92 cents per pound.
- Note: The Loan Redemption Rate (LRR) is the loan rate minus the current Loan Deficiency Payment (LDP).